These credit score tips explain the factors that affect your credit score, like payment history, credit enquiries, and default listings. You’ll also find practical, legitimate steps you can take to improve your credit profile over time. This guide covers what affects your score in Australia, plus broader financial wellness strategies for lasting financial health.
What Is a Credit Score in Australia and Why Does It Matter?
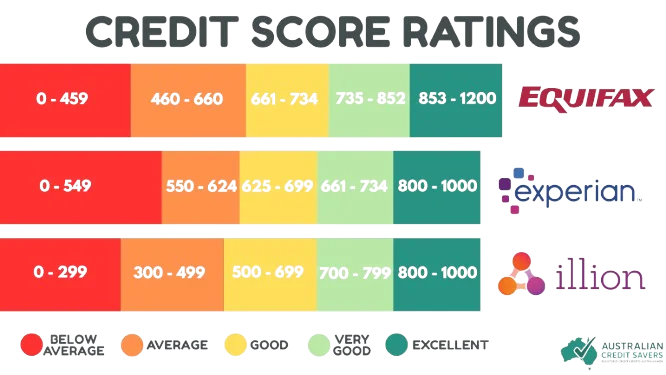
In Australia, a credit score is a number that reflects how reliably you manage credit and repayments, helping lenders assess the risk of lending to you. Australia has two major credit reporting bodies, Equifax and Experian, each maintaining its own scoring system. Equifax scores range from 0 to 1,200, while Experian scores range from 0 to 1,000, and their rating bands differ accordingly. Understanding good credit scores in Australia helps you interpret whichever bureau’s scale your lender uses.
Your credit score influences everything from mortgage approvals to mobile phone contracts. A stronger credit profile may improve the finance options or rates available from some lenders, although other lending criteria also apply.
Since 2018, Australia has used Comprehensive Credit Reporting (CCR), which means credit files include both positive and negative repayment data. On-time repayments now help build your credit history, not just missed payments hurt it.
What Factors Can Affect Your Credit Score in Australia?
Every credit file Australia lenders check is built from several components, each carrying a different level of influence on your score. Understanding what matters most helps you focus your efforts where they will have the greatest impact.
Payment History
Payment history is the most significant factor in determining your creditworthiness. Late payments are recorded as repayment history and can affect your score for up to two years, while defaults and court judgements can remain on your file for up to five years. Pay all bills on time, every time. For a more structured approach, proven debt repayment strategies can help you manage repayments more effectively.
Credit Utilisation
This measures how much of your available credit you are using. Keeping credit card balances below 30% of your credit limit demonstrates responsible credit management and signals to lenders that you are not over-reliant on borrowed funds
Length of Credit History
Longer credit histories generally result in higher scores, as they provide more data about your borrowing patterns. Unless there is an annual fee involved, keep your oldest credit accounts open to preserve your history length.
Types of Credit
Having various credit types such as credit cards, personal loans, and mortgages can positively affect your score. Keep in mind that more accounts do not necessarily mean a better score. Consistent, on-time payments are what truly matter.
New Credit Enquiries
Multiple credit applications in a short period can temporarily lower your score, as it may indicate financial stress or hardship. Only apply for new credit when absolutely necessary, and space out applications by at least six months when possible. Unauthorised or excessive credit enquiries on your file may also be disputable and credit enquiry removal is one of the services Australian Credit Savers can assist with.
How Do You Build Stronger Financial Wellness Beyond Your Credit Score?
Support a healthier credit profile by building good financial habits. The strategies below help you build a more stable financial position across the board.
Create and Stick to a Budget
The 50/30/20 rule is one budgeting approach some people use as a starting point. You might consider putting around 50% of your after-tax income towards needs, 30% towards wants, and 20% towards savings and debt repayment, then adjusting the split to suit your own situation.
Build an Emergency Fund
Many financial educators recommend building an emergency fund that covers several months of essential expenses, depending on your personal circumstances.
Review and Optimise Your Subscriptions
One of the most overlooked expenses is subscriptions. Conduct a monthly audit of recurring payments. Cancel services you do not actively use, and consider downgrading others. Many people pay for multiple streaming services, gym memberships, or software subscriptions they rarely use. If you have not yet checked your credit report in Australia, doing so reveals which accounts are appearing on your file and whether any need to be addressed.
How Can Australian Credit Savers Help You Improve Your Credit Profile?
Building stronger financial wellness and a healthier credit score takes time and consistent effort. Sometimes, even when you are doing everything right, your credit score may not improve as quickly as you expect. Inaccurate or invalid listings on your credit file, such as a default you were never properly notified about, or an enquiry you did not authorise,may negatively affect your credit profile, even if you have otherwise maintained responsible repayment behaviour.
That is where Australian Credit Savers can help. Australian Credit Savers holds Australian Credit Licence ACL 578002 and is an AFCA member (104645). The team specialises in assisting consumers with reviewing and disputing potentially inaccurate or incorrect credit report listings with a 5.0 rating across 400+ Google reviews. The team reviews your credit repair service in detail, identifies any negative listings that may be inaccurate or invalid, and works with you to prepare disputes through the proper channels. Correcting inaccurate or invalid listings may help improve the accuracy of your credit report and may support a healthier credit profile.
Services include Credit Enquiry Removal, Invalid Default Removal, Court Judgement Dispute Assistance, Repayment History Dispute Resolution, and Debt Negotiation and Settlement Support.
Australian Credit Savers operates on a No Win No Fee structure. A $330 non-refundable investigation fee applies at the start of any engagement, this fee is credited toward your total service fee if you proceed. Past outcomes do not guarantee future results.
Frequently Asked Questions
What is a good credit score in Australia?
A good credit score in Australia depends on which bureau is being used. Equifax rates scores from 0 to 1,200, with scores of 735 and above considered very good and 853 and above considered excellent. Experian uses a 0 to 1,000 scale, with a similar tiered structure. The higher your score within the bureau’s range, the better your borrowing prospects and access to lower interest rates.
How long does a negative listing stay on my credit file?
Most negative listings remain on your Australian credit file for five years from the date they are recorded. This applies to defaults, credit enquiries, and court judgements. If a listing is inaccurate or invalid, it can potentially be disputed and removed before the five-year period ends.
What is Comprehensive Credit Reporting (CCR) and how does it affect my score?
Comprehensive Credit Reporting (CCR) is the system introduced in Australia from 2018 that requires lenders to share both positive and negative repayment data with credit bureaus. Before CCR, only negative events like defaults were reported. Under CCR, consistent on-time repayments also appear on your file and actively contribute to building your score. This means good financial behaviour now directly helps your credit rating.
Can I dispute inaccurate information on my credit report?
Yes. Under Part IIIA of the Privacy Act 1988 and the Privacy (Credit Reporting) Code, you have the right to dispute information on your credit file that you believe is inaccurate, incomplete, or outdated.
How does improving my credit score help me get a home loan in Australia?
A higher credit score increases your chances of home loan approval and typically qualifies you for a lower interest rate. Lenders use your score as one of several indicators of risk. Borrowers with scores in the good to excellent range generally access a wider range of loan products, lower deposit requirements in some cases, and more competitive rates. Even a modest improvement in your score before applying can make a significant difference to the terms offered.
Your Next Step Toward a Stronger Credit Profile
Improving your credit score and building financial wellness in Australia works best as a long-term effort. Small, consistent actions, paying bills on time, reducing credit utilisation, reviewing your budget monthly, compound into meaningful improvements over time. If inaccurate listings are holding your file back, understanding your rights and getting the right support can accelerate the process significantly. Australian Credit Savers is here to help when you need it.
Get Your Free Credit Assessment Today
Australian Credit Savers offers a free credit assessment to help you understand exactly what is affecting your credit profile and what your options are. Whether you have a default, a court judgement, or enquiries you did not authorise, the team can review your file and walk you through your next steps. Contact Australian Credit Savers on 1800 844 185 or book online today.
Key Takeaways
- Australian credit bureaus (Equifax and Experian) each use different scoring scales, so check your score with the bureau your lender uses.
- Payment history is the single most influential factor in your credit score, and negative listings can remain on your file for up to five years.
- Comprehensive Credit Reporting (CCR) means consistent on-time repayments now actively improve your credit score, not just avoid damaging it.
- Keeping credit card utilisation below 30% of your limit and spacing out credit applications by at least six months both protect your score.
- Inaccurate or invalid listings such as unauthorised enquiries or improperly listed defaults can be disputed and potentially removed.
- A budget built around the 50/30/20 rule and an emergency fund of at least three to six months’ expenses form the foundation of long-term financial wellness.
- Australian Credit Savers is a licensed credit repair specialist with a 5.0 rating across 400+ Google reviews.